Find out what the accident really cost you.
Your car got repaired — but the day it went on record, its resale value dropped. We prove exactly how much, in a signed report that insurers and attorneys take seriously.
What brings you in today?
Answer a few quick questions — no cost, no obligation. If you qualify, we'll tell you exactly what a signed appraisal will cost and what happens next.
Two identical cars. One's been wrecked and repaired. Which one sells for more?
Same year, same miles, same flawless bodywork. But one has an accident on its history report. Almost every buyer picks the clean one — or demands a discount on the other. That discount is real money, and it's coming out of your pocket.
Illustration only. Your actual loss depends on your vehicle, the damage, and your local market — that's exactly what our appraisal measures.
The insurance company's first number is built to be low.
Their job is to close your file for as little as possible. Here's how the opening offer works against you — and how an independent appraisal flips it back in your favor.
A one-size-fits-all formula
Many carriers start from a rigid internal formula that caps your loss and barely looks at your car's make, condition, or what it'd actually sell for near you.
It's their number, not yours
The first offer is a starting point designed for them, not a fair settlement designed for you. It's meant to be accepted quickly and quietly.
You need independent proof
A signed, market-based appraisal replaces their opinion with evidence — and gives you the leverage to ask for what your car is really worth.
Three steps. About ten minutes of your time.
Upload your documents
Your repair bill, a few photos, and your vehicle details. About ten minutes, all online — no office visit, no phone tag.
We build your appraisal
A licensed appraiser pulls real market data for your exact vehicle and applies our published methodology — every figure disclosed, nothing hand-waved.
You get a signed report
A certified PDF in 3–5 business days, ready to send to the insurer or your attorney. Every report is signed and independently verifiable.
See exactly what you're buying
The report is the product. Comparables with the adjustment math shown, the full calculation chain, a signed certification, and the vehicle history that proves the accident record.
Cover — the conclusion, up front
Comparables with disclosed adjustments
The calculation, figure by figure
Signed certification with fingerprint
Vehicle history attachment
One flat fee. No percentage of your settlement.
No contingency and no percentage of your recovery. One flat fee for the report — everything you recover is yours.
Diminished Value
- Licensed market & comparable-sales analysis
- Published methodology, every figure disclosed
- Signed by a licensed appraiser
- Delivered in 3–5 business days
- Independently verifiable online
Total Loss Review
- Independent actual-cash-value analysis
- Comparable-vehicle market pull
- Shows what the insurer's offer misses
- Signed & ready to submit
- Same fast turnaround
Referred by a shop or attorney? Their discount code applies at checkout.
Owners who stopped taking the first offer.
Every claim outcome feeds our calibration log. As reports issue, this section fills with real numbers — never testimonials we can't stand behind.
“Geico offered me $32,945 for my totaled 4Runner. Cardinal's appraisal came in at $40,745, and I settled for $39,800 — almost $7,000 more than the first offer.”
[CLIENT QUOTE — pending first logged outcomes]
[ATTORNEY QUOTE — pending partner launch]
Everything you're probably wondering.
Can I claim if the accident wasn't my fault?
What if it was my fault?
How long do I have to file?
Do I need a lawyer?
What if the insurer ignores my report?
How fast will I get it?
Do you negotiate with the insurance company?
Do you work outside Arizona?
When the settlement offer doesn't add up
When an insurer declares your vehicle a total loss, they owe you its actual cash value — what it was genuinely worth the moment before the crash. That number comes from their valuation vendor, and it frequently trails the real market: the comparables skew low, the options and condition get averaged away, and the offer lands hundreds or thousands below what replacing your vehicle actually costs.
We prepare an independent actual-cash-value appraisal — built from licensed valuation data and documented comparable sales, adjusted to your exact vehicle, and signed by a credentialed appraiser. The same evidence standards and the same published methodology as every report we issue.
Owners use it to evaluate the offer before accepting, to support negotiation — their own or their attorney's — and, where a policy provides an appraisal clause, as the owner-appointed appraisal that clause calls for.
Understanding Vehicle Valuation Claims in Arizona
Arizona law recognizes circumstances in which vehicle owners may have claims involving loss in vehicle value. The information below explains some of the legal and valuation principles that may apply. It is general information, not legal advice, and the outcome of any particular claim depends on its facts, the applicable insurance policy, and governing law.
Is diminished value recoverable in Arizona?
What's the deadline?
Who actually pays?
What you'll need
What should a total-loss settlement reflect?
You may obtain your own appraisal
Built to survive an adjuster reading it
Licensed data behind every number
Archival valuations and market listings from licensed sources — cited by name and retrieval date in the report.
A published, versioned methodology
Every report states the methodology version it was prepared under. Change the rules, change the version.
Signed by credentialed appraisers
Name, credential, and certification on the signature page — with a compensation-independence declaration.
Every report verifiable by ID
A cryptographic fingerprint registered at signing. An altered copy fails verification — publicly, instantly.
The appraiser behind the signature
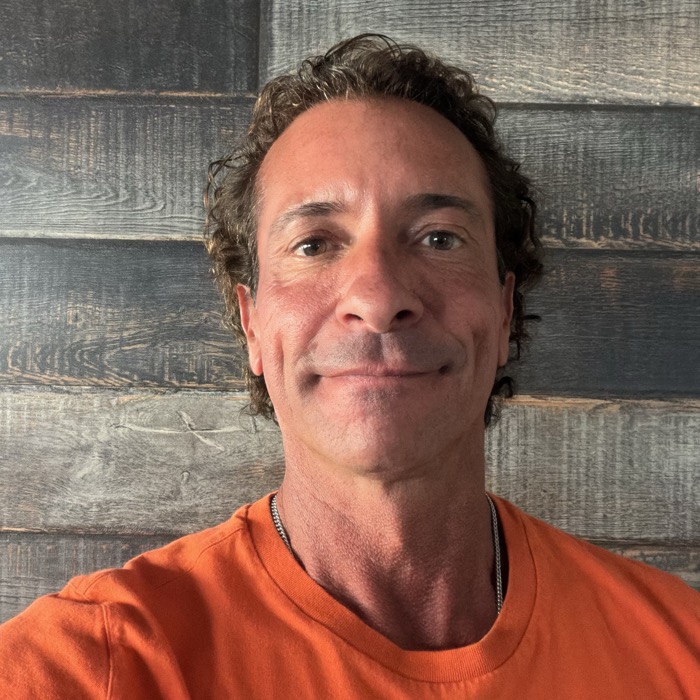
Ryan Chonka
Licensed Appraiser
Ryan has held an adjuster line of authority since 2009 and is licensed in Arizona, Texas, and Florida. He signs every report this firm issues — sixteen years of reading repair files from the carrier's side of the table is exactly what makes a valuation hold up when a carrier reads it back.
Arizona Adjuster License #14641509 — Active (resident)
Effective through 08/31/2029 · also licensed in Texas (Adjuster — All Lines, #1671971, since 2011) and Florida (Adjuster — All Lines, non-resident) · NPN 14641509 · Adjuster line of authority held since 2009 · verifiable on the NAIC state licensing registry · Errors & omissions coverage: [E&O CARRIER & POLICY]
The appraisal half of your property damage practice, handled
Upload clients in minutes, track every request through a dedicated portal, and receive signed reports delivered directly to your office — with partner pricing and a discount code your clients can use. Your client hears from you, not from us.
Talk to the firm
appraiser@cardinalappraisalgroupllc.com
14555 N. Scottsdale Rd. Ste. 320, Scottsdale, AZ 85254
Monday–Friday, 8am–5pm MST
Attorneys: mention your firm in the message and we'll set up partner access and portal credentials.
Ready to find out what you're owed?
The eligibility check is free and takes about a minute. You'll know right away whether it's worth pursuing.
Check if I qualify — it's free